Blog > Seller Guide > General
Voluntarily Surrendering a Car to the Bank in the Philippines: What to Check First
AI-generated illustration of an owner reviewing a generic document; not an actual customer or lender transaction.
Voluntary surrender means arranging to return a financed vehicle to the lender. Before handing it over, get the proposed terms in writing: what happens to the car, how the account will be calculated, and whether any amount will remain payable. Do not assume that returning the keys cancels the debt or protects your credit record.
This guide helps Philippine car owners prepare questions and compare options. It does not determine what you owe or which remedy a lender can legally use in your case.
Key takeaways
- Separate the vehicle handover from the lender’s written settlement terms and account confirmation.
- Ask for current figures and compare any repayment change, lender-approved sale and surrender option before deciding.
- Keep signed records. A sale or surrender cannot be promised to erase accurate negative credit information.
Does surrendering the car clear the loan?
Do not treat a receipt for the car as proof that the loan is fully settled. In the 2016 Navarro v. Rural Bank of Tarlac decision, the Supreme Court recorded a dispute after a vehicle was surrendered and sold. The acknowledgment of receipt did not establish the borrowers’ claimed full-payment agreement. That historical case illustrates the importance of evidence; it is not a ruling on your contract.
Ask the lender whether it proposes to accept the vehicle as full settlement or to sell it and apply the proceeds to the account. Request the written basis and an itemized calculation for any amount it says would remain due. Whether a claimed balance is legally recoverable needs assessment of your documents and applicable law—not a general online formula. If you dispute it, consult a Philippine lawyer before accepting the claim or signing a waiver.
Start with a written account picture
Contact your lender through a verified channel. Ask for the loan agreement, payment history, current statement and a full-settlement computation valid for your intended payment date. Ask which charges are included and whether the figure can change.
For example, BDO’s Auto Loan page provides a route to request loan documents and a full-payment computation. It also distinguishes full payment and bank clearance from the later release of collateral documents. This is BDO’s published process, not a uniform procedure or deadline for every bank.
Compare those records with your receipts. Raise unexplained charges or missing payments in writing and keep the reference number. Do not rely only on the monthly installment or an informal estimate of the car’s value.
Compare three options with your lender
1. Ask whether a repayment change is available
Explain what you can realistically afford and ask whether the lender offers a suitable change to the payment arrangement. Request the proposed monthly payment, term, total cost, fees and credit-reporting treatment. Asking does not mean the bank will approve restructuring or a payment holiday.
Do not treat a request or negotiation as permission to stop paying. Ask the lender to confirm in writing what is due while it considers your request.
2. Explore a sale with lender-confirmed settlement steps
Ask whether and how a sale can be coordinated with the lender. Confirm the amount required, who receives payment, any gap you must fund, and when documents can be released. For the detailed selling process, see our guide to selling a financed car safely.
Planning example only: a lender’s written settlement quote of ₱600,000 minus sale proceeds of ₱550,000 leaves a ₱50,000 funding gap before any additional costs not already included. This is arithmetic for an agreed-sale scenario—not a calculation of legally recoverable debt after surrender or foreclosure. An offer is not a completed sale.
Do not assume a private “pasalo” arrangement transfers your loan obligations. Ask the lender for its written decision and the required documents before acting on any proposed change of borrower.
3. Request the voluntary-surrender terms
If you are considering surrender, ask the lender for its own checklist and proposed agreement before booking a handover. Confirm these points:
- Who is authorized to accept the vehicle, and where should it be delivered?
- Which identity documents, vehicle records, keys and signed forms are required? Who currently holds the originals?
- Is the proposal full settlement, or will the vehicle be sold and the account calculated afterward?
- How will any sale proceeds, expenses, claimed balance or surplus be accounted for, and when will you receive the statement?
- What written acknowledgment and account-status confirmation will you receive?
This is a question list, not a universal bank requirement. Read every completed form, request a copy and clarify any waiver or unclear wording before signing. Keep a handover record identifying the vehicle, recipient, date, keys/documents received and recorded condition. A handover acknowledgment and confirmation of full settlement serve different purposes.
Will voluntary surrender protect your credit record?
There is no credit-protection guarantee. TransUnion Philippines explains that credit reports include payment history, outstanding debt and overdue accounts, and that late payments and defaults can affect a score. A different handover method does not justify promising a clean credit record.
Ask your lender how it will report the account and when it will update any settlement. Review your credit report and challenge errors using the relevant provider’s official process. TransUnion’s current contact page directs consumer credit-report disputes through its Lista partner app; check that page for the current route.
If the lender’s response is unclear or disputed
First use the bank’s customer-service or formal consumer-complaint channel. BSP’s Consumer Assistance Mechanism is a second-level route for unresolved concerns involving BSP-supervised institutions; follow its published instructions and retain the bank’s response or evidence of your complaint. Do not include passwords, PINs or sensitive identification documents in a BSP complaint. Its guidance sets out what to provide and what to exclude.
BSP’s route does not cover every lender: the same guidance directs financing/lending-company complaints to the SEC. If court papers arrive or a debt or waiver is disputed, obtain appropriate Philippine legal advice rather than assuming an online complaint settles the legal issue.
A short decision checklist
- Get written figures: payment history, settlement quote and proposed surrender terms.
- Compare the options actually offered: affordability, total cost, sale funding gap and written surrender outcome.
- Clarify before signing: recipient, required documents, accounting and account-status confirmation.
- Keep records and check updates: handover evidence, lender correspondence and accurate credit reporting.
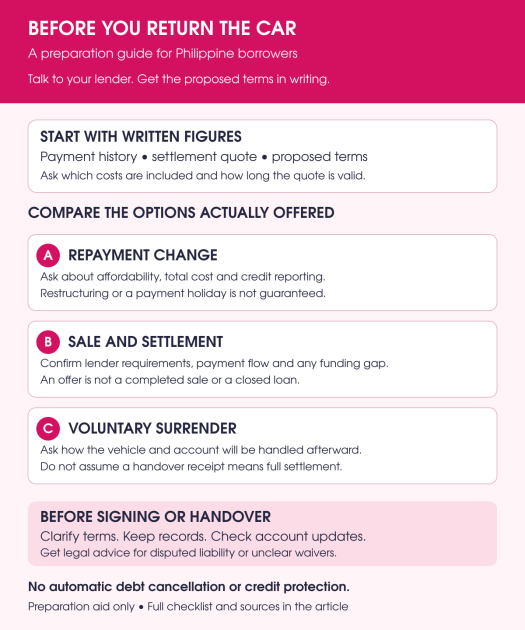
A preparation aid—not a debt-cancellation promise. The complete checklist and qualifications are in the text above.
Common questions
Can I just leave the car at a bank branch?
Arrange the handover with the lender first. Confirm the authorized recipient, location and written terms; do not assume an unarranged drop-off closes the account.
Do I always need the original OR/CR?
Ask your lender. Confirm who holds the Official Receipt and Certificate of Registration and what it requires for your specific handover. This guide does not prescribe a universal originals checklist.
Can Mobee guarantee a sale before repossession?
No such guarantee is made here. If you want to explore selling, contact Mobee Cars Philippines at +63 960 399 9990. PH inspections are free and there are no seller fees. Disclose the financing status and ask about eligibility and the steps that can be supported for your case. The lender must confirm its own settlement requirements.
Sources checked: 27 October 2026. General information only; individual debt, contract and legal questions need advice based on the actual documents.
Was this article helpful?
How to Spot a Fake OR/CR in the Philippines
17 April 2025 Mobee Cars PhilippinesHow to Check Flood-Prone Areas in the Philippines: Official Resources for Car Owners
15 November 2024 Mobee Cars PhilippinesHow to Sell a Financed Car in the Philippines
27 February 2025 Mobee Cars PhilippinesNo comment yet. Be the first to comment.